

Commercial Loans

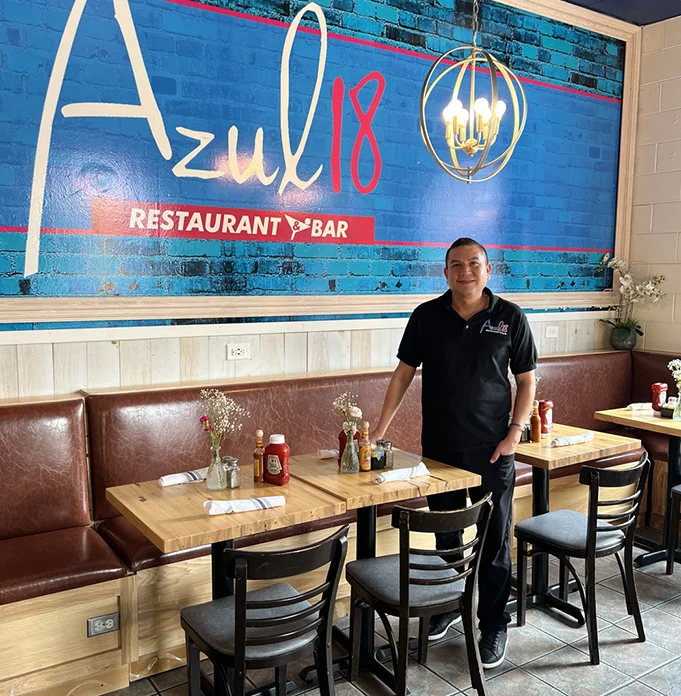
Loan funds supported key upgrades at beloved Chicago eatery, Azul 18.
A financing partner that's there for you
With more than 40 years of experience, we know how to help your business or nonprofit succeed. We offer a variety of loan products to fit your needs. And when you need someone to go the extra mile? We've got your back.
Business, Nonprofit, and Faith Loans
Loans for existing businesses, nonprofits and religious organizations.
Commercial Real Estate Loans
Commercial and mixed-use properties in low-income communities.
Multifamily Housing Loans
Loans for developers and owners of 5+ unit multifamily rental housing with recent, relevant experience.
Affordable Housing Loan Funds
Bridge and gap financing for multifamily affordable housing in select geographies.
Charter School Loans
Loans for public charter school facilities that create and expand quality educational opportunities for students.
New Markets Tax Credit Loans
NMTC allocation and source loans are available for building or renovating education or health care facilities.
Commercial Loans FAQs
We provide commercial loans for small businesses, nonprofits, and large commercial real estate projects. Typically, our loans are traditional real estate-secured term loans used for things like property acquisition, construction, expansion or renovation. For small businesses and nonprofits, we also offer loans for working capital and equipment purchases.
Our commercial loans are available in most states where we have a Self-Help branch. Charter school lending is available in all states. Some programs or loan sizes may only be available in certain areas. Submit an inquiry form to see if we can meet your needs.
Generally, we offer loans of $500,000 and up. There is no maximum loan size.
In North Carolina and the greater Chicago area, we also offer loans below $500,000.
We do not offer commercial loans under $15,000.
We offer other financing options, like personal loans, through our branches. Contact your local branch to ask about:
- Loans for less than $15,000
- Consumer loans
- Vehicle loans
We do not currently offer lines of credit.
We can sometimes lend to startups in the childcare industry.*
For all other industries, we generally do not lend to startups. We define a startup as any of the following:
- A new business or nonprofit
- A business or nonprofit that has filed fewer than two years of tax returns
- A business or nonprofit that you plan to purchase but do not currently manage
* For child care startups, we generally lend no more than $50,000. We require the borrower to provide collateral, a 30% owner's investment in the business, and a secondary source of income that can cover both personal expenses and the new loan payment.
We do! Nonprofit financing is one of our specialties. Please note that we may require a personal guaranty.
We do, within certain parameters:
- We only consider residential real estate investments that have explicit affordable housing or workforce housing components.
- Our primary focus for commercial loans is multifamily properties.**
Please reach out to our commercial lending team if you're unsure whether your project is a good fit.
**For 1-4 unit properties: We offer small investment property mortgages for individuals who qualify. Reach out to our home lending team to inquire about these loans.
Yes. Self-Help participates in the SBA 7(a) and 504 programs. Our lending team has deep expertise in SBA financing, and we'll work with you to find the best option for your project.
- SBA 7(a): A good fit for businesses that have enough cash flow to repay the loan but lack sufficient collateral or operating history to obtain a traditional loan.
- SBA 504: A good option for low down payment, long-term financing to acquire or improve major fixed assets, such as owner-occupied real estate or machinery/equipment with a 10-year (or longer) useful life.
To explore whether an SBA loan is right for your project, submit an inquiry form and our team will reach out to you.
We look at your whole credit report, not just your score. While having a healthy credit score is best, we can consider lower scores. If your score is on the low end, having a 12-month history of on-time payments for a credit line, rent, or utility bill can help. A borrower with a lower score may need to have a co-signer.
Unfortunately, we cannot lend to your business if you have a judgement against you or are in bankruptcy.
We typically require real estate as collateral to fully secure commercial loans. The larger the loan, the more collateral we will need.
We can sometimes be flexible on this requirement if you have an otherwise strong application, including a good credit score and some equity to put into the project. We also sometimes have programs to help cover collateral gaps.
If you're not sure about collateral, reach out to our team to ask. We're here to help.
It depends on what you're using the loan for, and how much money you've already invested in your project. We usually like to see a 10-25% equity contribution from a borrower toward their project.
Working capital loans usually do not require an equity contribution.
Start by filling out our interest form with information about your project. A member of our team will get back to you within a few days to get more details about your project. If your project is a good fit, you'll fill out an application and get connected to a loan officer.
From here, the process and timing will vary depending on the complexity and size of your project. For a small working capital loan, the process generally takes 6-8 weeks from submitting your application to receiving your funds, and you'll work with a small team.
For more complicated projects, like a multimillion-dollar affordable housing construction loan, you may need additional team members, deeper review, and several months to approve and finalize your loan.
Regardless of your loan's size or complexity, our team will be asking lots of questions so that we can best meet your needs.
If you have questions about what this process would look like for your specific project, contact us.
It depends on your project, but in general, you'll need:
- 2-3 years of business tax returns/financial statements
- A project budget
- 2-3 years of personal tax returns for all borrowers and guarantors
- Cash flow projections
For projects that include construction, you'll also need to provide a site plan, a project schedule, and a description of your architect/general contractor.
We'll let you know exactly which documents to include with each application. As we proceed through the loan process, we may request additional documentation.
Submit a commercial lending inquiry form. Our team will reach out to you with instructions for what to do next.
Contact us via email at [email protected] or give us a call at (844) 218-7083.