

What Is the Homebuying Process?

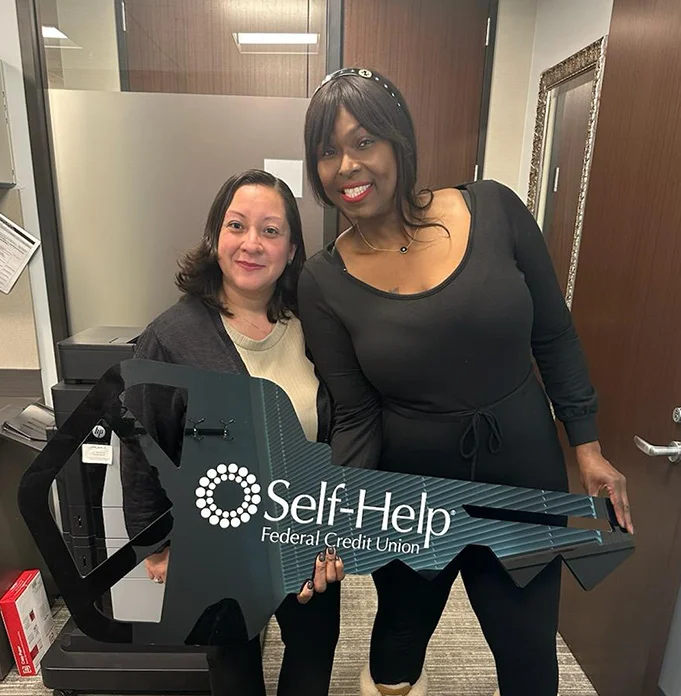
Sanrena Howard, pictured with Self-Help Mortgage Loan Officer Margarita Jaramillo.
Self-Help offers a FICO® Credit Review that is free to members, or you can check your score for free with the major credit bureaus.
The credit score you need to qualify for a home loan will vary based on the loan type. It is recommended to aim for 700 or higher, but our lowest minimum credit score is 580.
Our FICO Review experts can help you come up with a plan. You might consider our CreditBuilder loan, which was created to help you build credit, or a secured credit card.
Use your income and expenses to decide how much home you can afford. There are many mortgage calculators that exist online, but you may want to consult a financial coach for more accurate support.
There is a misconception that you need a 20% down payment to purchase a home. While a higher down payment can have benefits, if you qualify for our Equity Boost loan, you may need as little as 1% cash to close.
You might have discovered that you are closer to homeownership than you think, but if you still have some work to do, come up with a saving goal. For a personalized financial plan and guidance, get in touch with one of our wealth and wellness coaches.
Finding a loan officer that you trust is essential. Our experienced loan officers will talk with you to understand your goals and your financial situation. Even if you're not sure you're ready, don't hesitate to reach out.
Submit a pre-qualification application along with supporting documents like your tax returns, W2s, pay stubs and bank statements. If you pre-qualify for a loan, we’ll issue a pre-qualification letter.
Pre-qualification letters help establish you as a serious buyer by showing sellers that you have mortgage financing lined up.
Your trusted loan officer may have recommendations for real estate agents. You can also ask friends and family for recommendations. Meet with potential agents to find someone you’re comfortable working with.
Prepare for your home search by making a list of your needs, wants, deal breakers and areas where you’re willing to compromise. Your real estate agent will help you find properties in your price range that meet your needs.
You'll probably tour a number of homes in your budget. Once you've found the right one, your agent will help you make an offer and navigate any negotiations. Depending on your location, you may have to do this more than once, as some housing markets can be pretty competitive.
After your offer is accepted, your real estate agent will help you line up a home inspection. The inspector will examine the property and let you know about any issues or necessary repairs, particularly any that might impact your decision to buy the house.
Now that you've found a home, it's time to come back to your loan officer to submit a full mortgage application.
Your loan officer will give you a loan estimate, which lays out exactly how much you can expect to pay at closing and over the life of the loan. This is also the step at which you’ll lock in your interest rate.
This step typically takes between 35-45 days, but we'll keep you informed. During this time, we order an appraisal for the property, coordinate with any down payment assistance providers, underwrite the loan and more.
In the last few days before closing, you’ll have a chance to review the final paperwork and ask any questions.
At the closing meeting, you’ll pay closing costs and any down payment that was determined. You'll also sign the loan documents and get the keys to your new home.
Once closing is complete, you’ll officially be a homeowner! Welcome home!